Is Co-Signing a Good Option for an International Student Loan?
It is well known that getting an international education can cost a lot of money, especially if tuition and living expenses exceed the savings and scholarship amount of a student. Many international students find it challenging to get private loans for studying abroad due to a lack of financial qualifications or a sufficient credit history. Some lenders can require a co-signer from a student, and in some cases, they will offer better conditions if a financially qualified person signs a loan along with the borrower.
Having a co-signer for an international student loan can facilitate the process of getting a loan as well as provide better terms for the borrower. Nevertheless, this option requires serious consideration. It is not about the possibility of getting a loan but also about financial responsibility. A co-signer is responsible for repayment of the loan if the borrower fails to make payment.
Therefore, it is necessary for international students to think about the possible pros and cons of having a co-signer before turning to their relatives or friends for help.
What Does a Co-Signer Mean in Terms of an International Student Loan?
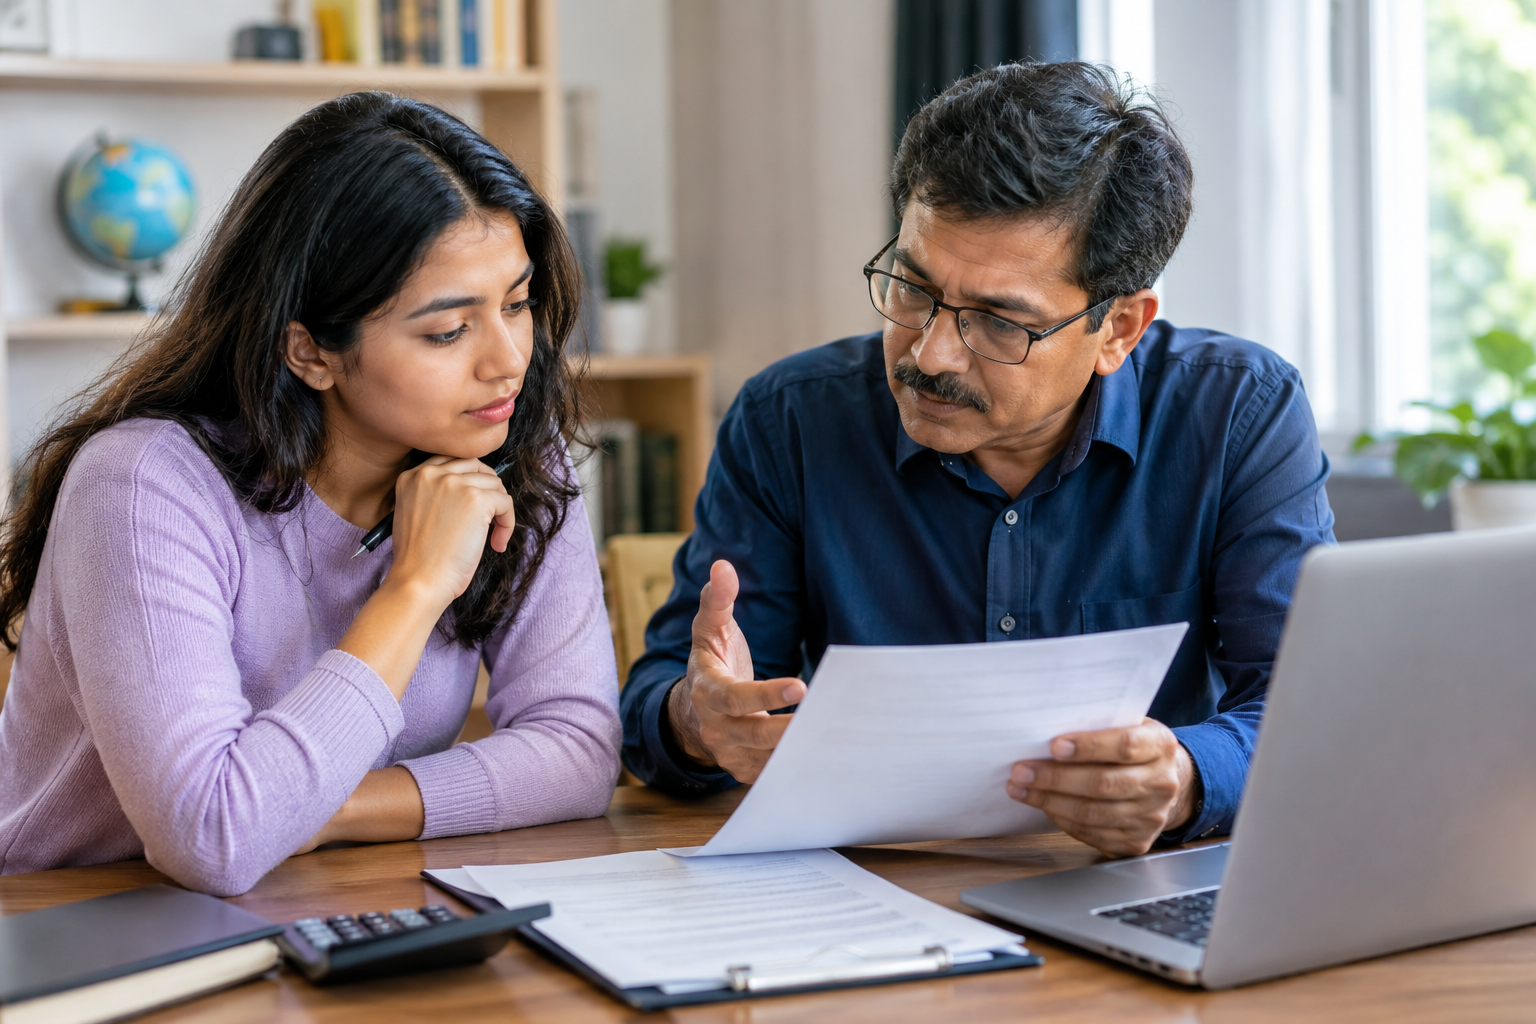
A co-signer is a person who will repay the loan along with a borrower. Lenders may require such co-signers in case applicants lack the necessary financial qualifications or sufficient credit history. If a person who signs the loan together with the applicant has a good credit profile, then it may result in obtaining a low-interest loan.
This is quite an actual issue for international students who do not have any credit history in another country where they are planning to study. Thus, the lender will use the financial qualifications of the co-signer during the assessment.
The most crucial thing about being a co-signer is that this status provides financial obligations. It means that a co-signer will have to repay the loan in case a borrower fails to pay it.
Pros of Using a Co-signer for an International Student Loan
Higher Chances of Loan Approval
First of all, using a co-signer might increase the likelihood of being approved for the loan since a financial institution will look at the co-signer as someone who reduces risks connected to the payment process. It is important to remember that a lot of students with little credit history and recent arrivals need the help of an experienced co-signer.
Thus, a co-signer is required by some lenders when private students want to get a loan without any previous credit history.
Nevertheless, there might be other conditions that the borrower should fulfil besides the presence of a co-signer.
Potentially Better Interest Rates
Having a co-signer with an excellent credit record might positively influence the interest terms that a student is going to pay.
The Consumer Financial Protection Bureau states that if a student is going to have a co-signer, they will get the loan with lower interest terms.
It might make a huge difference in the total payments since lower interest means lower interest payments throughout the whole repayment period.
Students should not be sure that all the lenders are going to offer them a lower interest rate in case they have a co-signer. All the interest rates depend on the underwriting policies and the financial condition of the borrower.
Potentially Higher Borrowing Capacity
If the co-signer is qualified, they may increase the loan amount. In this way, it will be possible to cover the existing gap in money needed for covering educational costs.
However, increasing the amount of the loan does not mean that students should borrow too much money. The recommended amount is the amount needed to cover educational costs without the possibility of obtaining scholarships or saving money.
Access to More Loan Options
There are some private institutions that require having a co-signer from an international student. That is why, with the help of a co-signer, there is the opportunity to access additional loan products.
Cons of Using a Co-signer for an International Student Loan
The Co-signer Is Responsible if You Cannot Repay
This is the main disadvantage. The co-signer becomes responsible for paying back the loan according to the respective loan agreement. If the borrower stops paying off the loan, the co-signer may also be obligated to make the payments. And if the loan goes into default, it will affect the co-signer too.
It is especially relevant to the case of an international student, because future employment and income may be uncertain. The student may experience trouble finding a job, changing countries, having unexpected expenses, or having a low-income period after graduation.
The co-signer thus must have the financial ability to make payments on behalf of the borrower.
Missed Payments Can Hurt the Co-signer’s Credit
Any issues with payments can affect both participants of a co-signed loan. According to the CFPB, delays or non-payments on a co-signed loan for the student will affect the credit records of the co-signer and borrower.
And it is important because the co-signer may want their credit score to be good for other reasons – mortgage, car loans, credit cards, etc.
The fact that the co-signer does not get the money for the loan does not make this risk disappear. They remain financially linked to the debt.
It Can Cause Financial Tensions Between the Borrower and Co-Signer
The student loan lasts for several years, which makes the co-signing arrangement a long-term financial commitment.
Financial tensions can happen when the borrower has trouble paying the loan and when the co-signer expects the student to do it without any obstacles. It will cause conflict with family or friends.
Both of them should discuss the repayment expectations and responsibilities beforehand. The co-signer should be aware of the possibility of paying the loan themselves.
Co-signer Release May Not Be Automatic
Some private lenders provide co-signer release, which allows the co-signer to opt out of the loan agreement once certain requirements are fulfilled. These requirements can be a certain number of consecutive monthly payments and a creditworthiness re-evaluation.
Never expect that paying your bills on time will automatically release the co-signer. It all depends on the lender and loan agreement.
Make sure that both the co-signer and the borrower learn in advance if the loan is eligible for release, when exactly the borrower can apply, what financial requirements must be met, and whether there is any guarantee of approval.
What to Check Before Signing a Co-signed International Student Loan
The interest rate is just one thing to keep in mind. Study the entire loan agreement. Pay special attention to the repayment period, monthly payment, any fees, start date of repayment, and whether the interest rate is fixed or floating.
Take a look at what happens in case of non-payment of the loan. You have to know the lender’s procedure for dealing with defaults and how you remain responsible for the loan.
Also, pay attention to the policy of co-signer release and find out whether it exists, what conditions apply, and how to apply for it. Most lenders provide co-signer release options; however, they are different depending on the loan.
Keep in mind that both the student and co-signer have to be aware of the total cost of repayment, not just the initial loan amount. The CFPB suggests reviewing the loan terms and thinking about the willingness and ability of the co-signer to repay a loan in case of default.
Co-signer vs. No Co-signer: What Is the Real Trade-off?
The option to apply for a loan with a co-signer could offer access to loans that would not be available otherwise and better terms due to a better credit score of the co-signer. Nevertheless, the responsibility is divided between two people.
A loan without a co-signer is more independent, but there may be differences in eligibility, interest rates, and the loan limit. There are also differences between federal and private student loans, and the lenders of the latter have the freedom to establish their own terms.
It is, therefore, not just a choice between a co-signer and no co-signer. Check what loan offers are actually available to you. You should compare the total amount of the repayment, monthly payments, fees, interest rate, and obligations of the co-signer.
Conclusion: A Co-signer Can Help, but It Comes With Real Responsibility
A co-signer for an international student loan could resolve an important financing issue. A good credit standing of the co-signer could lead to the approval of the loan, lower the interest rate, and make the loans accessible.
However, the use of a co-signer for the loan is associated with serious financial consequences, such as the co-signer making the payment on behalf of the student and the negative impact of late payments on the credit scores of both people.
In this regard, the use of a co-signer should not be regarded as a matter of routine. The student and co-signer should know the whole loan agreement, the cost of repayment, possible consequences of default, and the terms of release.
A loan with a co-signer could be an effective solution for financing an international education when the loan amount is affordable, and both parties are aware of all the risks. The best loan is not just the one that was approved. It is the loan that could be reasonably taken into account by both sides.
Contact Us
Contact us for a free consultation for student or visitor visas. Our immigration experts are ready to assist you.